AI-generated scene
Oil prices ripple through trucking, packaging, fertilizer, and electricity before landing on your grocery bill and utility statement. The fix is a seven-lever counterattack: lock in fixed-rate expenses, buy bulk smart, upgrade efficiency, protect savings, negotiate every bill, and know when to actually rework your goals instead of just riding it out.
Here's the deal: gas prices tick up a dollar, and three weeks later your grocery bill looks like it went through boot camp. Eggs cost more. The electric bill creeps. Your streaming subscriptions somehow never go down, but everything connected to a truck, a tractor, or a power plant does.
That's not bad luck — that's oil working its way through the whole economy, one invoice at a time. This guide is the counterattack: where the money actually leaks, and what a dad with a plan does about it.
Trucks move roughly 72% of all freight tonnage in the country, and every one of them runs on diesel. Oil climbs a few dollars a barrel, diesel follows within days, and the trucking company passes that cost straight to the manufacturer. The manufacturer passes it to the distributor. The distributor passes it to your grocery store, and your grocery store passes it to you — nobody in that chain eats the cost for fun.
Packaging takes a second hit most dads never see coming. Plastic bottles, shrink wrap, cereal bags, and most food containers start life as petroleum byproducts. When crude goes up, the plastic that wraps your kid's cereal gets more expensive to make before the cereal even touches the truck.
Fertilizer runs on natural gas, not oil directly, but the two markets move together often enough to matter. Nitrogen fertilizer costs climb, farmers pay more to grow corn and soybeans, and that cost rolls downstream into everything fed on those crops — beef, chicken, dairy, eggs. That's why a spike at the pump shows up in your egg carton a month later looking like a coincidence. It isn't.
Then there's the utility bill sitting on your kitchen counter. Natural gas and oil generate a meaningful share of U.S. electricity, and when fuel costs rise, power companies file for rate increases to cover it. Your thermostat didn't change. Your usage didn't change. The input cost behind the switch on your wall did.
Every link in that chain adds a markup. By the time oil finishes its trip from the ground to your grocery cart, it's touched transportation, packaging, farming, and the power grid — and billed you for all four.
Real talk: you can't control the price of a barrel of oil, but you can control how many of your bills are allowed to move with it. That's the whole game here — find every expense still exposed to the weather and nail it to the floor.
Start with your mortgage. A fixed-rate mortgage means your principal and interest never change no matter what the Fed does or what oil does to inflation — it's one of the few 30-year promises you'll ever get in writing. If you're still floating on an adjustable-rate loan while rates climb, that's a conversation with your lender worth having now, not after the next hike lands.
Utilities aren't all created equal either. Some providers offer fixed-rate electricity or natural gas plans, usually locked for 12 to 24 months, trading a slightly higher starting rate for protection against mid-contract spikes. In deregulated energy markets, dads can shop providers directly instead of taking whatever the default utility hands them.
Insurance renews annually, which means your rate is never actually fixed — it's just quiet until it isn't. Ask about multi-year rate locks or policies with capped annual increases, especially on home and auto, where inflation and repair costs have been pushing premiums hard.
None of this stops oil from moving. It just decides how much of that movement gets to touch your checking account. Lock down what you can, and the variable stuff left over gets a lot easier to manage.
Bottom line: bulk buying saves money when you do the math, and costs money when you do the vibes. The rule is simple — compare unit price, not sticker price. A 40-ounce jar of peanut butter at $9 beats three 16-ounce jars at $4 each, but you only know that if you check the per-ounce number printed on the shelf tag instead of trusting your gut.
Shelf-stable goods are where bulk buying actually pays off: rice, dried beans, canned vegetables, pasta, paper products, and anything that sits in a pantry for a year without complaint. Perishables are where it turns into a trap — that warehouse-size bag of spinach doesn't care about your good intentions, and half of it hits the trash by day five. If it rots, freezes badly, or goes stale before you'll realistically finish it, the "savings" was never real.
Buy bulk on things your family uses on a predictable schedule — diapers, toilet paper, laundry detergent, coffee — not on things you're hoping you'll suddenly start eating more of. A deal on quinoa nobody in the house likes isn't a deal, it's clutter with a receipt attached.
Watch the storage math too. A membership warehouse case of anything takes up real square footage, and a garage full of bulk goods you can't rotate through fast enough just turns into an expensive shelf. Bulk buying is a budget tool, not a hobby — buy what you'll use, store what you can rotate, and skip the rest.
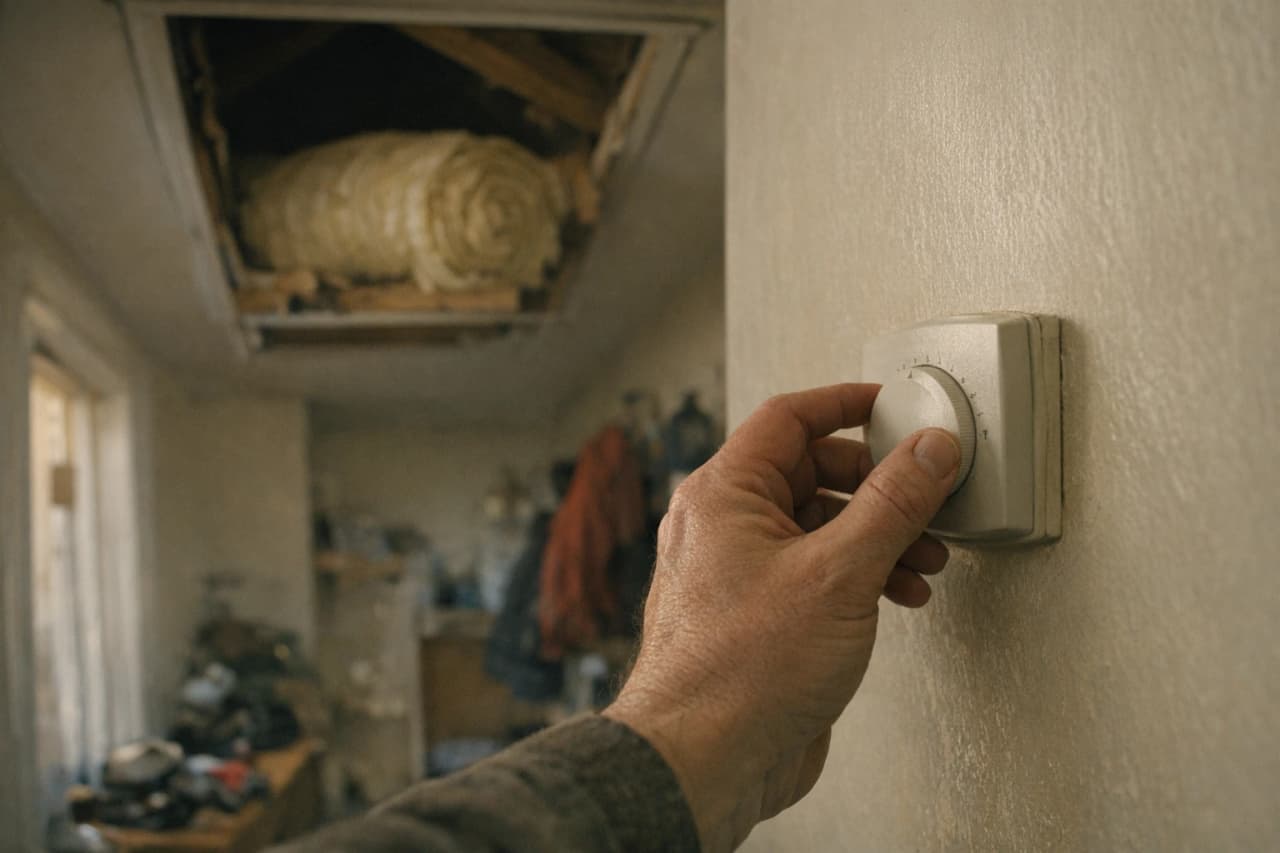
Here's where the math actually works in your favor: energy upgrades cost money once and save you money every month after, which is the opposite of everything else inflation does to you. A programmable or smart thermostat runs $25 to $250 depending on how fancy you get, and the Department of Energy puts the savings around 10% a year on heating and cooling just from not babysitting the dial yourself. You set it once. It does the work every single day you forget about it.
Insulation is the boring upgrade nobody brags about, but attics losing heat through gaps and thin coverage are one of the biggest energy leaks in an average house. Adding insulation in an underinsulated attic can cut heating and cooling costs by 15% or more, and unlike a lot of home projects, it's one a lot of dads can knock out themselves over a weekend.
LED bulbs use about 75% less energy than old incandescent bulbs and last 15 to 25 times longer, which means you're not just saving on the power bill — you're buying lightbulbs a whole lot less often too. Swap the whole house out and it's one of the cheapest upgrades on this list with one of the fastest payoffs.
Appliances matter more than most dads think. An ENERGY STAR-certified refrigerator uses roughly 9% less energy than a standard new model, and when you're replacing an appliance that's 10-plus years old, the gap gets even bigger. None of these upgrades stop oil from moving — they just shrink how hard it gets to hit you when it does.
Cutting expenses only gets you half the win — the other half is making sure the money you've got left doesn't quietly lose ground while it sits in the bank. A standard savings account paying 0.4% isn't protecting anything when inflation runs hotter than that; it's just losing slower than cash under the mattress. High-yield savings accounts, the kind offered by most online banks, have been paying well above that in recent years, and moving your emergency fund there costs nothing but ten minutes and a routing number.
Series I Savings Bonds are built for exactly this fight. The interest rate adjusts twice a year based on inflation, so when prices climb, your return climbs with them instead of getting left behind. They cap at $10,000 per person per year through TreasuryDirect, and you can't touch the money for the first 12 months, which makes them a fit for savings you weren't planning to spend anyway — not your emergency fund.
None of this replaces a real financial plan, and I'm not your advisor — talk to one before you move real money. What I am qualified to say is that doing nothing isn't neutral. Cash sitting still in a low-interest account is losing value every month inflation runs hot, whether you're watching or not.
The other side of the hedge is income, not just savings. A side gig — freelance work, selling a skill you already have, a weekend hustle — doesn't need to replace your paycheck to matter. It just needs to outpace the squeeze. An extra $300 a month doesn't fix inflation, but it buys back some of the ground it's taking from you every time you fill up the truck.
Most dads let bills renew on autopilot, which is exactly how insurers and cable companies count on you behaving. Real talk: every one of those companies has a retention department whose entire job is to keep you from canceling, and that department has more room to negotiate than the first person who answers the phone.
Start with insurance. Call your home and auto carrier once a year and ask directly: "What discounts am I not currently getting?" Bundling policies, raising your deductible, or qualifying for a safe-driver or loyalty discount can shave 10% to 25% off a premium without changing your coverage at all. If the answer is nothing, get a quote from two competitors — a lot of carriers will match or beat a competing offer just to keep you on the books.
Subscriptions are even easier. Call and say the word "cancel," not "can you help me" — that phrase routes you to retention, not customer service, and retention reps are the ones holding the actual discount codes. Cable, internet, and streaming bundles regularly knock 20% to 40% off for customers willing to have that conversation instead of just eating the renewal rate.
Service contracts — pest control, lawn care, alarm monitoring — work the same way. Most renew automatically at a higher rate than new-customer pricing, and a five-minute call asking to match the new-customer deal usually gets it done. If you got time to lean, you got time to clean — and if you've got ten minutes once a year, you've got time to call.
Bottom line: every lever in this guide so far is tactical. This one is strategic — the question of whether your actual goals, not just your monthly habits, need to change. That's a different decision, and it deserves more than a gut check at the gas pump.
Short-term price spikes don't move the needle. Oil jumps for a quarter, groceries tick up, you tighten the bulk-buying and call a few bills — that's riding it out, and it's the right call most of the time. Inflation has been volatile for decades, and a family that overhauls its entire financial plan every time crude swings is going to be exhausted and broke from whiplash, not ahead of anything.
Sustained pressure is different. If your real, inflation-adjusted income has been losing ground for 12 months or more — raises not keeping pace with your actual cost of living, not just the headline CPI number — that's not weather, that's climate. That's when a college fund timeline, a retirement contribution rate, or a house upgrade plan needs an honest second look, not a white-knuckle grip on the original number.
The test I'd use: can you still hit your savings targets without cutting something load-bearing — your emergency fund, your retirement match, your family's actual quality of life? If yes, hold the line. If you're quietly raiding savings just to keep the old plan alive, the plan is the problem now, not your discipline.
God can move mountains — but you'd better bring a shovel, and sometimes the shovel means admitting the five-year goal needs to become a seven-year goal instead of a slow bleed.
None of this makes oil cheaper. It just decides how much of that cost actually reaches your kitchen table, and that part's on you.
So don't try to fix all seven levers this weekend — you'll quit by Tuesday. Pick the one with the fastest payoff: pull up your bank statement, list every recurring bill on it, and call the three most expensive ones. Insurance, cable, a service contract — doesn't matter which. Ask what discounts you're not getting, and say "cancel" if you have to.
That's an hour of your Saturday for a discount that compounds every month after. Sometimes good enough is good enough — just make sure it's good enough on purpose, not by accident.
FAQ
One email a week — only when there’s something new. No spam. No sponsors.
Unsubscribe anytime · Privacy